We’ve replaced the By the Way newsletter with KCU Connect, a refreshed format designed to share stories, deliver timely updates, and highlight the news that matters most to Kentucky’s credit unions. With clearer sections, quick links, and a more community-focused approach, KCU Connect will make it easier to stay informed and connected across our movement.
Have an announcement or news article you would like to submit? Send us an email!
In Washington, D.C.
Advocacy, as you know, is a long-term endeavor and one that requires constant and consistent investment. One such form of investment is through our trips to D.C., one of which occurs in the fall, this year taking place September 15 through 17.
During our Hike the Hill, as the event is called, we meet with elected officials or staff members from Kentucky, including both of our Senators and all six of our Members of the House of Representatives, to discuss our most pressing issues and to reinforce the importance of credit unions to all their members and communities across Kentucky.
Often, all that work and time invested in building relationships and educating elected officials can feel hard to quantify without tangible, visible results, which is why it’s so heartening to see the below entry in Senator Paul’s most recent constituent newsletter.
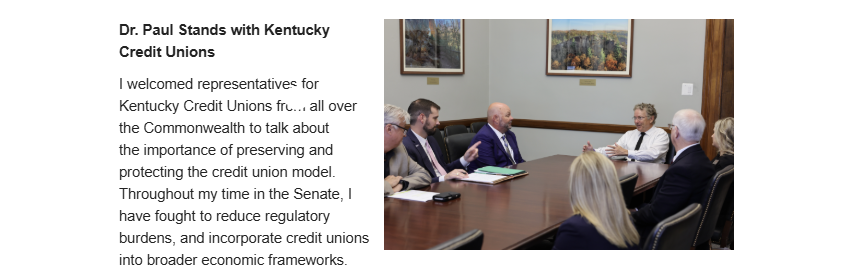
Not only did Senator Paul highlight that he spoke with credit unions, but he also took the step to state that he affirmatively “Stands with Kentucky Credit Unions.”
What This Means for You
I share this to demonstrate that your investment in advocacy does not go unnoticed and that elected officials are paying attention to what we say. So, please stay informed and engaged, and stay tuned for future opportunities to continue strengthening your advocacy muscles.
Please reach out with any questions or if we can be of service in any way.
Sincerely,
Kyle Hagerty
SVP & Chief Advocacy Officer
November 6-8 | French Lick Resort | French Lick, IN
The 2026 Board & Committee Leadership Conference is coming to French Lick Resort, November 6-8, with a new weekend format featuring education designed specifically for credit union volunteers, networking, family-friendly activities and more.
There are a few important dates and deadlines coming up:
Make your plans now and join us for a weekend of education, connection and fun in French Lick!
October 14 & 15, 2026 | Virtual Training
The highly skilled Ascensus trainers present virtual IRA workshops covering essential and advanced IRA topics, delivered right to your desk!
THIS TRAINING IS A COLLABORATION WITH TENNESSEE CREDIT UNION LEAGUE.
Ascensus is the nation’s premier provider of IRA services for credit unions, with training options that cover the full range of IRA topics from basic to advanced. Whether you are new to IRAs or an experienced administrator wanting an update on this year’s new rules, you’ll find the training you need to serve your members’ IRA needs.
REGISTER FOR THE SESSION THAT MEETS YOUR TRAINING NEEDS.
(Link takes you to the Tennessee League website.)
October 21, 2026 | League Office
9:00 a.m.–3:00 p.m. ET
Small credit unions may have limited time and resources, but they also have unique strengths that can create opportunities for growth.
Join us virtually on October 21 for the Small Credit Union Symposium, featuring practical sessions designed specifically for smaller credit unions. You’ll hear from industry experts and leave with ideas you can put to work right away.
Sessions include:
Get It Done Marketing for Small Credit Unions
Learn how to turn scattered marketing efforts into a clear, repeatable plan, use AI to save time and build a 30-day marketing plan you can begin using immediately.
The Puzzle-Solving Approach That Enables Small Credit Unions to Thrive
Discover how small credit unions can use their agility, strong community connections and member focus to turn perceived disadvantages into competitive strengths.
Working with Your Examiner
Gain practical guidance from NCUA Supervisory Examiner Craig Bilotta on reducing exam friction, sharing information effectively and aligning expectations early in the examination process.
The program is designed for credit unions with assets of $100 million or less, but all credit unions are welcome to attend.
Connect with your peers, gain practical insights and leave with strategies you can implement at your credit union.
Part I: Tuesday, October 20, 2026
9:00 am - 1:00 pm EDT
Part II: Thursday, October 22, 2026
9:00 am - 1:00 pm EDT
Educational Investment: $225 for a Webinar Connection and Archive link
In partnership with the Indiana Credit Union League, Branch Manager Leadership Virtual School is offered as a two-part series.
Part I- October 20, 2026
This session will cover:
Part II - October 22, 2026
This session will cover:
Who should attend?
New and experienced Branch Managers, Assistant Branch Managers, Teller Supervisors, Lead Frontline Professionals and any professional aspiring to lead the team in a retail branch.
Registration deadline: Friday, October 16, 2026
November 10, 2026 | 2:00 PM ET | Virtual
Stay up to date and meet your annual BSA training requirements with a practical review of the Bank Secrecy Act and your responsibilities as a credit union employee. This session will cover BSA/AML fundamentals, recognizing and reporting suspicious activity, common red flags, and other key compliance responsibilities employees need to know.
Starting October 1st, webinars from the Credit Union Webinar Network are BUY GET ONE FREE! Here's what's included with our On-Demand sale webinars:
Access anytime, anywhere: share unlimitedly and view on desktop, mobile, or tablet 24/7.Remember, these on-demand sale webinars have no expiration. Access them anytime through your User Portal and even download them for offline training.
Don't miss out on this incredible offer! Sale ends October 15th.
A statement issued by NCUA and other federal regulators Wednesday clarifies confidentiality requirements related to Suspicious Activity Reports (SARs) and communications with members or customers.
This statement emphasizes that the Bank Secrecy Act (BSA) and its implementing regulations generally permit communications to members/customers that include discussions of suspicious transactions, account restrictions or closures, and fraud concerns, as long as those communications do not disclose that a SAR was filed.
While it does not alter existing BSA legal or regulatory requirements or establish new supervisory expectations, it does include SAR confidentiality details and examples of communications with a financial institution customer “typically not prohibited by the BSA.”
America’s Credit Unions Compliance Blog examines the joint interagency statement in today’s entry.
Source: www.americascreditunions.org
On August 5, 2026 the National Credit Union Administration (NCUA) finalized 11 rules under Phase One of its Deregulation Project . The NCUA issued 31 rules in Phase One, which launched in late 2025, of the Deregulation Project. This leaves approximately 20 of the original Phase One proposals still pending final action. The NCUA is also continuing to review additional regulations, so the project isn't necessarily limited to those 31 proposals. The agency describes the project as an ongoing, “multi-year initiative to review, streamline, and modernize the agency’s regulatory framework”.
The new rules were published in the Federal Register on August 6, taking into consideration public comments received from each proposed rule, and take effect on September 8, 2026. According to the NCUA, these rules remove obsolete or burdensome requirements and give credit unions more operational flexibility.
Four of the rules are Interpretive Rulings and Policy Statements (“IRPS”), finalized as proposed, that rescind requirements already incorporated into the Chartering and Field of Membership Manual. IRPSs provide agency guidance on existing law and policy without creating new, binding, legal requirements through formal rulemaking. In other words, they don’t create new legal obligations that weren’t already contained in the underlying statute or regulation. Instead, they clarify ambiguous language or explain how the agency will interpret existing requirements. The rescinded IRPS’s are as follows:
IRPS 06-1 Organization and Operation of Federal Credit Unions: Limits the number of sources FCUs must check to ensure compliance with applicable chartering and field of membership requirements. This rescission reduces the burden for federal credit unions (FCUs) by limiting the number of sources that FCUs must check to verify compliance with applicable requirements.
IRPS 08-2 Service to Underserved Areas: Provides modifications to the Chartering and Field of Membership Manual to update and clarify the process of approving credit union service to “underserved areas. This rescission reduces the burden for federal credit unions (FCUs) by limiting the number of sources that FCUs must check to verify compliance with applicable requirements.
IRPS 10-1 Community Chartering Policies : Sets forth the NCUA’s current Field of Membership policies and procedures. This rescission reduces the burden for FCUs by limiting the number of sources that they must check to verify compliance with applicable requirements.
IRPS 11-02 Federal Corporate Credit Union Chartering : States that it is reasonable to rely on the Federal Corporate Credit Union Chartering Manual for NCUA guidance and procedures on corporate FCU chartering. The rescission reduces regulatory burden by limiting the number of sources FCUs must review to ensure compliance with laws and regulations.
The other seven rules are as follows:
Suretyship and Guaranty; Segregated Deposit and Collateral – 12 CFR 701.20(c)(3) and 701.20(d) : Credit unions no longer need to set aside funds or collateral from the member to cover the risk when they guarantee a member’s obligation.
Limits on Loans to Other Credit Unions – 12 CFR 701.25(b) : Removes the requirements for a federal credit union board of directors to approve loans to other credit unions.
Notice of Termination of Excess Insurance Coverage – 12 CFR 741.5 : Removes the 30-day notice requirement prior to a credit union’s termination of excess share insurance coverage and instead requires federally insured credit unions to notify members some time before the termination of excess coverage.
Requirements for Insurance – 12 CFR 741.10 : Eliminates a notification requirement that federally-insured credit unions were already required to make as part of their agreement for maintaining federal share insurance.
Purchase, Sale, and Pledge of Eligible Obligations – 12 CFR 701.23 : Removes the prescriptive list of items that must be included in federal credit union written policies around the purchase, sale, and pledge of eligible obligations. Also, strikes the provision regarding conflicts of interest and compensation, which are also covered in credit union bylaws and other NCUA rules.
Credit Union Service Contracts – 12 CFR 701.26 : Formally clarifies that credit unions may serve as representatives in shared operational arrangements with other credit unions or organizations, minimizing compliance complexity by removing extraneous requirements.
Third-Party Servicing of Indirect Vehicle Loans – 12 CFR 701.21(h) : Removes two sections of regulations that limited a federally insured credit union’s purchases of indirect auto loans serviced by a third party to 50% of its net worth.
What’s Next?
There are 20 proposed rules that remain outstanding for Phase One and the NCUA expects a second phase to start in 2027 which will be another multi-year initiative. However, this phase will address more complicated regulations with “broader policy or operational implications”, anticipating “rulemaking activity that requires additional analysis, stakeholder engagement, or longer implementation timelines”.
The top-of-mind question always is: how does this impact my credit union? NCUA’s Deregulation Project presents an opportunity for credit unions to provide feedback through public comment periods, stay informed about regulatory changes, and evaluate whether proposed or final changes could meaningfully affect policies, procedures, practices, or examination focus. While not every proposal will affect every credit union, many will make it important to pay attention to the overall direction of the project. Over time, these changes could reduce compliance burdens in certain areas, clarify regulatory expectations, and eliminate requirements that no longer align with current credit union operations.
Source: www.americascreditunions.org
As we wrap up our final KCU Connect Lunch of the year, we want to say thank you for another wonderful year of connection. We’ve loved the conversations, the laughs, and the opportunity to spend time together throughout the year. A special thank you to Morgan Pottinger McGarvey for sponsoring our KCU Connect Lunches and helping make these gatherings possible. We’re already looking forward to more time together next year!
Join us for our final KCU Connect Lunch of the year on Wednesday, October 28, at Selena’s at Willow Lake Tavern in Louisville!
Come enjoy lunch, connect with fellow credit union professionals, and catch up with your KCU team in a relaxed setting.
**Seating is limited, so RSVP early to reserve your spot!**
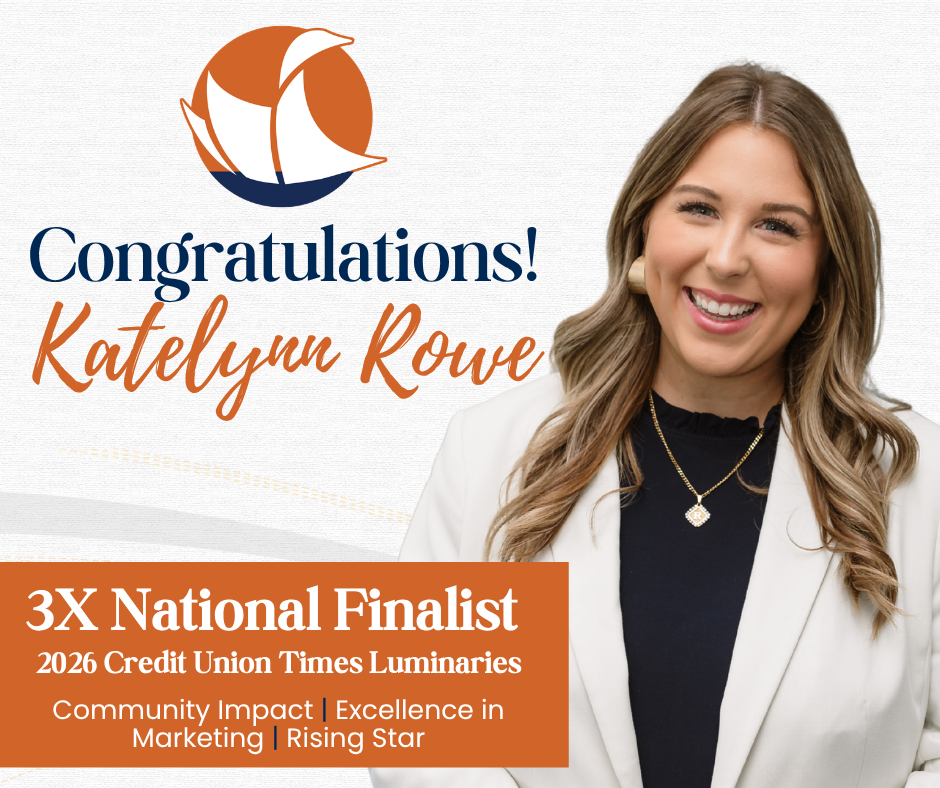
Signet Federal Credit Union® has been named a finalist in three categories of the 2026 Credit Union Times Luminaries Awards, earning national recognition for Community Impact, Excellence in Marketing and individual leadership. Signet is a finalist for Community Impact — $1 Billion & Below and Excellence in Marketing — $1 Billion & Below, while Katelynn Rowe, Vice President of Marketing and Communications, has earned national recognition as a Rising Star — $1 Billion & Below finalist for the second consecutive year.
.png?width=940&height=788&name=Jan.%2028%20(1).png)
The Credit Union Times Luminaries Awards recognize individuals, teams and organizations that are driving meaningful change and innovation throughout the credit union industry. Finalists will receive national recognition through CUTimes.com and Credit Union Times' digital channels in the months leading up to the awards ceremony.
“To be recognized nationally in three different areas is incredibly meaningful because each one represents a different part of who we are as a credit union,” Rowe said. “Community impact reflects why we exist. Marketing gives us the opportunity to tell those stories and connect people with the resources available to them. And to personally be recognized as a Rising Star alongside that work is something I’m incredibly grateful for. None of these recognitions happen because of one person—they are a reflection of a team that genuinely believes in what we do and the communities we serve.”
Founded in 1939 by local railroad workers who pooled their resources to help one another, Signet has remained rooted in the cooperative philosophy of People Helping People for more than 87 years. Today, that philosophy continues through financial education, community partnerships, local outreach and storytelling designed to strengthen connections with members throughout Western Kentucky.
The Community Impact finalist recognition highlights Signet’s commitment to extending its mission beyond traditional financial services and investing time, resources and education into the communities it serves. The Excellence in Marketing recognition reflects the credit union’s continued focus on authentic, community-centered storytelling and campaigns designed to make financial services more relatable, accessible and meaningful.
Rowe’s Rising Star finalist recognition represents the individual leadership category among credit unions with $1 billion or less in assets. As Vice President of Marketing and Communications, Rowe leads Signet’s marketing, communications, public relations, community engagement and brand strategy, with an emphasis on connecting the credit union’s history and cooperative mission to the needs of today’s members.
The recognition adds to a growing year of state and national industry recognition for Signet. Earlier in 2026, the credit union earned its first-ever America’s Credit Unions Diamond Award, receiving Category’s Best in Brand Awareness for its Voices of the Vault campaign. Signet has also received recognition at the state level through Kentucky’s Credit Unions, further highlighting the credit union’s impact across the Commonwealth. The 2026 CU Times Luminaries finalist selections continue that momentum, recognizing Signet across Community Impact, Excellence in Marketing and Rising Star and reflecting the credit union’s growing impact in marketing, community service and leadership.
Credit Union Times will publish finalist profiles from Sept. 8 through Oct. 30, with winners selected by the Luminaries judging panel. The 2026 Credit Union Times Luminaries Awards dinner and gala will take place Nov. 5 in Orlando, Florida, where winners will be announced and honored live.
“Being a credit union from Western Kentucky and seeing our work recognized on a national stage is something our entire team can be proud of,” Rowe said. “You don’t have to have the largest budget, the biggest team or the most resources to make a meaningful impact. You have to know who you serve, understand why your work matters and be willing to show up for your community every single day. That’s what our team continues to do, and I think these recognitions are proof that meaningful work can come from organizations of any size. Together, we are Signet.”
The Omicron Nu Lambda Education Foundation (ONLEF), Abound Credit Union and the Swope Family of Dealerships are joining forces again to improve the financial future of more Hardin County residents.
Through the partnership, all Hardin County residents are invited to participate in Dave Ramsey’s Financial Peace Program FREE! In the true spirit of teamwork, ONLEF will provide a presenter for the series, Abound is sponsoring the cost of the program for the Education Foundation, and Swope will provide their dealership Community Room in Elizabethtown to host the series.
The weekly sessions will be held in-person on Saturdays beginning September 26 at 10am ET.
Program Dates: Every Saturday between September 26 and November 21 at 10am ET
Location: Swope Toyota Community Room
1085 North Dixie Highway, Elizabethtown, KY 42701
Hardin County residents interested in the program may register online here.
“At Abound, we believe that expanding access to financial education benefits all Kentuckians,” says Jake Darabos, CPA, Chief Finance & Administration Officer for Abound Credit Union. “We’re proud to once again sponsor the Omicron Nu Lambda Education Foundation to help others achieve more and improve their financial health.”
“At Swope, we believe that a strong community begins with strong families. Providing access to financial education gives our neighbors the tools to build stability, reduce stress, and create a better future for their households. We’re proud to partner with Abound and Omicron Nu Lambda to offer resources that uplift Hardin County and empower the people who live and work here,” says Jennifer Swope, COO, Swope Family of Dealerships.
“Abound’s ongoing support allows us to provide more individuals with a proven plan for financial success so they can take control of their money and change their lives,” says Carl Millsap, Education Foundation Chair. “Omicron Nu Lambda has a legacy of service and deep commitment to the Hardin County community.”
In addition to Abound’s community partnerships, free online learning tools and financial education resources for Kentuckians of all ages are available at www.aboundcu.com.
Service One Credit Union has announced the promotion of Lucretia "Cree" Patrick to Human Resources Manager. Bringing years of human resources expertise to the role, Patrick will oversee daily HR operations, employee relations, and talent development across the credit union.
Patrick has been with Service One for 4 years and most recently has been in the HR Generalist role.
"Cree is a valued member of our team and a trusted HR partner, consistently demonstrating a genuine commitment to our associates,” said Michelle Dyer, Chief People and Strategy Officer. "We are excited to see her leadership growth and look forward to the impact she will continue to make.”
Patrick holds a Bachelor of Arts in Psychology from Western Kentucky University. A native of Birmingham, Alabama, she currently resides in Bowling Green. Active in the community, she is a member of Alpha Kappa Alpha Sorority, Inc. Outside the office, she enjoys shopping and cherishes spending time as a proud "Nana" to her grandson.
Abound’s Dollars & $ense Personalized Financial Counseling Program, a free, one-on-one financial coaching initiative to help participants build confidence and achieve long-term financial wellness, recently won the statewide Desjardins Adult Financial Education Award.
“Financial education is most effective when it’s personal, practical, and tailored to an individual's unique circumstances,” says Ray Springsteen, President & CEO of Abound Credit Union. “By connecting participants with one of our 31 nationally certified Credit Union Financial Counselors, Abound is helping create lasting change for our fellow Kentuckians.”
The Dollars & $ense program provides individualized support through a structured 4-session coaching model. Sessions are in person or virtual, removing transportation and scheduling barriers. Participants work directly with an Abound counselor to identify goals, evaluate spending habits, create savings and budgeting plans, understand credit factors, and develop strategies to reduce financial stress and build long-term stability.
In just the first four months of the program, Members completing the counseling process experienced credit score increases, an increase in savings, and debt reduction. Here are what a few recent participants had to say:
“I just had my final meeting with my counselor last week. I was able to refinance a loan, reducing my interest rate from 27% APR to 18% APR. When I started this journey, my goal was to get myself in a better financial standing to eventually purchase my own home and vehicle. I’m confident I’m on the right track. This was worth my time, without a doubt. I even have $500 sitting in my savings account right now, which is a first for me.” – Radcliff Member
"I finished my final session with my counselor. My end goal is to buy my own home. I’m finally on a path to do that. Through this program, I’ve not only made my car payments on time, but I’ve put $1,000 additional toward my principal balance. I plan to keep this pattern which means my car will be paid off three years early! I was able to get approved for my first credit card and I finally feel like I have a cushion for emergencies, something I’ve never had before.” – Bowling Green Member
“When I started this program I truly didn’t think the Abound counselor would teach me anything I didn’t already know. While I’m not a big saver, I’m also not a big spender so I thought it all evened out. Little did I know what opening a High Yield Savings account would do for me. I found myself with a few hospital bills and instead of using my credit card to pay them off, I was able to get into my Savings account to pay exactly what I needed. It was nice to be set up for a tight financial decision without going into debt. My financial knowledge has increased in ways I didn’t expect and I’m grateful I made time to finish this program.” – Elizabethtown Member
Through these individualized coaching relationships, Abound empowers individuals to make informed financial decisions that strengthen both their personal financial well-being and the overall health of their communities. Dollars & Sense is part of Abound's broader commitment to financial education throughout Kentucky.
Learn more about Abound’s financial wellness initiatives at AboundCU.com.
Signet Federal Credit Union® earned five national awards and was selected as one of only four MACQUEE finalists at the 2026 Marketing Association of Credit Unions (MAC) Awards, bringing the Western Kentucky credit union’s total to seven national awards in 2026.
A record 548 entries were submitted for this year’s MAC Awards. From those submissions, national judges selected Signet’s Start with Kindness campaign as one of four finalists for the MACQUEE, MAC’s Best in Show recognition.
The selection advanced Signet to a live competition at the MAC Conference in Scottsdale, Arizona, where Vice President of Marketing and Communications Katelynn Rowe took the stage to pitch Start with Kindness before hundreds of credit union marketers and industry professionals from across the country. After all four finalists presented their campaigns, conference attendees voted to select the MACQUEE winner.
“To be chosen by the judges as one of four campaigns to make it to that stage was an incredible recognition on its own,” Rowe said. “But what made this one especially meaningful was getting to stand in front of other credit union marketers from across the country and tell them about Western Kentucky, our members and why Start with Kindness mattered to our community. Everything we create starts with knowing exactly who we work for — our members.”
Signet received five additional MAC Awards in the Under $750 Million asset category:
Gold — Social Media
Silver — Innovative Marketing
Silver — Community Engagement
Silver — Public Relations
Bronze — Community Engagement
The recognition is especially significant for Signet because Start with Kindness was conceptualized, developed and executed entirely in-house by the credit union’s one-person marketing department with a campaign budget of less than $500.
“For a credit union from Western Kentucky to compete on a national stage alongside campaigns backed by much larger teams and resources says something important about what is possible when you truly understand the people you serve,” Rowe said. “Impact isn’t always determined by the size of the budget. For us, it starts with listening to our members and creating something that reflects the community we call home.”
That philosophy is rooted in Signet’s cooperative structure. Unlike a shareholder-owned financial institution, Signet is owned by its members. There are no outside shareholders to serve, allowing the credit union to focus its programs, products and community initiatives on the people who own it and the Western Kentucky communities it serves.
Start with Kindness was created with that purpose in mind. Rather than asking the community to simply watch a marketing campaign, Signet invited individuals, families, businesses and organizations to participate in weekly acts of kindness and share those actions with others.
The five MAC Awards add to the national recognition Signet received earlier this year for its Voices of the Vault campaign from America’s Credit Unions, including Category’s Best in Brand Awareness at the 2026 Diamond Awards. Combined, Signet has earned seven national awards in 2026.
“We don’t have outside shareholders asking us to put their interests first. Our owners are the people walking into our branches, raising families here and building our communities,” Rowe said. “That is who we work for, and that is who we want our work to represent.”
Signet Federal Credit Union® is a member-owned financial cooperative serving 11 counties throughout Western Kentucky. Membership begins with a $5 share deposit, giving eligible members an ownership stake in the credit union.
The FDIC Just Counted Us. Now Let's Make Sure It Counts Us Right.
For decades, federal bank regulators measuring local competition acted as if credit unions barely existed. When a bank merger came up for review, credit union shares were typically discounted or left out of the math entirely. That changed last week.
On September 17, 2026, the FDIC issued a notice of proposed rulemaking to modernize and reform its framework for reviewing transactions under the Bank Merger Act. Buried in the technical detail is a significant shift: the initial Herfindahl-Hirschman Index (HHI) screen would be revised to treat the deposits of banks, thrifts and credit unions equally for purposes of market share calculations.
In plain English, Washington is formally acknowledging what Kentuckians already know. When a family in Pikeville or Paducah chooses where to keep their savings or finance a truck, a credit union is a full competitor in that decision.
Why this matters
The practical effect runs mostly in one direction. According to Sullivan & Cromwell's analysis, these changes generally would make it easier for banks to merge in markets with a significant thrift or credit union presence. In rural Kentucky counties where a credit union holds a meaningful share of local deposits, bank consolidation just got easier to approve.
That is not necessarily bad news. But it carries two implications our movement should think about carefully.
First, recognition cuts both ways. Being counted as an equal competitor for merger purposes will inevitably be cited in conversations about tax status, perhaps including the study now underway here in Frankfort. Our answer should be confident and calm: credit unions compete for members' business precisely because of the cooperative structure, not in spite of it. Member ownership, reinvested earnings, and community focus are what we bring to the market, and that difference is the point.
Second, the methodology matters. Where only some of a credit union's branches are within the relevant geographic market, the FDIC would estimate the credit union's shares in that market by dividing its total shares by its total number of branches and multiplying the result by the number of branches located in the market, using the most recent NCUA Call Report data. That shortcut can misstate a credit union's real footprint, especially for institutions with a large headquarters office or members who bank mostly online.
What we're doing
The FDIC is seeking comments on all aspects of the Proposal and has included more than 100 specific questions. Comments are due on November 23, 2026. National trade groups are already engaging; one says it supports elements of merger reform but objects to provisions governing credit union buyers and how their competitive presence is measured.
Kentucky credit unions, particularly those in rural and multi-county markets, have real-world data that can sharpen the record.
We have long asked to be taken seriously as a competitive force. The FDIC has now done so. Our job is to make sure the accounting is accurate.
Sincerely,
Jim Kasch
League President